The era of cheap money is over. What higher rates mean for you
Published in Business News
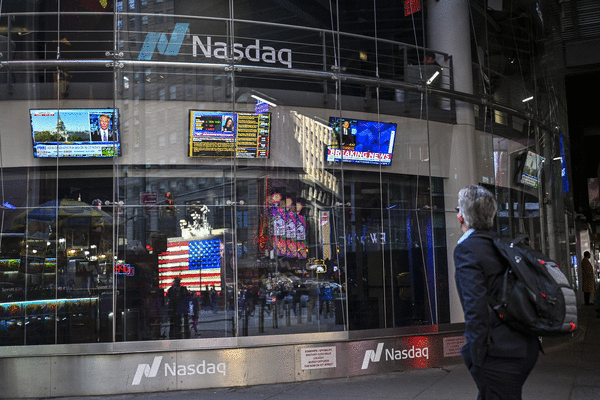
Remember when you could get a mortgage for 2.5%?
Those days seem almost as distant as dial-up internet and $1 gallons of gasoline.
Americans are living in an economy where everything is expensive — and the latest quarter-point interest rate increase by the Federal Reserve will make the cost of borrowing money higher too.
“The U.S. is a consumer-based economy,” said Bernard Carter, president of Carter Wealth Strategy based in Pittsburgh.
“As consumers face higher costs for mortgages, credit cards and auto loans, this may put a damper on overall demand, which can negatively affect the general level of stock prices,” he said.
The Fed raised its benchmark federal funds rate by a quarter percentage point last week, to a target range of 3.75% to 4% — its first rate increase in more than three years. The move was aimed at fighting inflation that has refused to go down as quickly as policymakers would like.
For consumers, the consequences are already showing up in some very familiar places.
Mortgage rates have climbed back over 7%, putting another squeeze on homebuyers already dealing with historically high home prices. The average 30-year fixed mortgage reached about 7.2% on Sept. 23, according to Bankrate.
Credit card borrowers are facing another increase in the cost of carrying a balance. Auto lenders are adjusting their baseline rates higher too, meaning the cost of financing cars is about to get more expensive.
And it’s not just consumers feeling the pressure.
The U.S. government is one of the world’s biggest borrowers, and higher interest rates mean it must pay more to finance its enormous debt. At the same time, businesses face higher costs when they borrow to expand, invest or refinance existing debt.
“The Fed only controls the overnight lending rate from bank to bank. Yes, banks borrow from each other every day,” said Paul Brahim, managing director of Wealth Enhancement Group in Pittsburgh.
”When the Fed sets this rate, all other rates, as determined by the market, tend to follow suit,” Brahim said. “Essentially, the fed funds rate direction is the barometer for future market activity. Markets key off of that rate.”
Higher rates mean harder hits on households
The era of cheap money is over.
For more than a decade, Americans became accustomed to extraordinarily low interest rates. Mortgages could be had for rates as low as 2.5%, however, investors had few alternatives to stocks when savings accounts and government bonds paid next to nothing.
That world is gone.
The United States has more than $40 trillion in federal debt, while American households are carrying trillions of dollars in mortgages, credit card balances, auto loans and other debt. Higher rates mean that all of that borrowed money becomes more expensive to maintain or refinance.
“Last year, the federal government spent nearly $1 trillion on interest,” said Maya MacGuineas, president of the Committee For a Responsible Federal Budget, based in Washington, D.C.
“That’s about three times what we spent in 2020 and 2021 and more than we spend on defense,” MacGuineas said. “With interest rates high and rising, interest costs are slated to explode from here.”
But there is another side to the interest rate story that hasn’t received nearly as much attention.
Higher interest rates are finally giving savers and conservative investors something they haven’t had in years — a meaningful return for simply lending their money.
The yield on the 10-year U.S. Treasury note topped 5% after the Fed’s announcement, reaching levels not seen since 2007 — outside of a brief period in 2023. The Treasury’s 10-year yield stood at 5.06% on Sept. 23.
But there’s a catch to those juicy yields. What investors earn on their money isn’t necessarily what they gain in purchasing power.
‘Cash no longer has to sit idle’
Michael Godwin, chief investment officer at Fragasso Financial Advisors in McMurray, Pennsylvania, said investors need to consider why rates are so high in the first place.
“Investors who are moving heavily into cash because short-term interest rates are attractive should remember that the reason rates are elevated matters,” Godwin said.
“If rates are high primarily because of inflation concerns, investors may be earning a higher nominal return on their cash, but inflation is simultaneously eroding their purchasing power.”
Nonetheless, higher rates offer a silver lining for savers and conservative investors. After years of watching their money earn next to nothing, they finally have places to park cash where it can earn a decent return.
That means cash no longer has to sit idle earning next to nothing.
Treasury bills, money market funds, certificates of deposit and other fixed-income investments can provide yields that would have seemed amazing during the era of near-zero interest rates.
Godwin said when the Federal Reserve raises rates, it is generally trying to slow the economy and bring inflation under control.
He said stock market investors need to consider that as economic growth slows companies may face pressure on their margins and profits, which can ultimately weigh on stock prices.
“Even in a rising rate environment, there are certain areas of the stock market that can perform relatively well,” Godwin said.
“Banks, for example, can benefit from higher interest rates because they are able to earn more on loans and other interest-bearing assets.”
How debt can eat into profits
Energy companies can also be attractive when rates are rising because of inflation concerns.
“Energy prices tend to be closely tied to inflation, so energy stocks can provide investors with some protection against rising prices,” Godwin said.
On the other hand, higher interest rates often put pressure on some of the markets most rate-sensitive sectors.
David Root Jr., CEO of DBR & Co. in Pittsburgh, said utilities and real estate investment trusts, or REITS, can be particularly vulnerable.
“These are often bought for their dividend yield, which becomes less attractive when bonds start offering competitive yields with lower risk,” Root said. “They also carry a lot of debt, so financing costs rise.”
The list doesn’t stop there. Root said high-growth and unprofitable technology companies can also come under pressure because higher interest rates make future earnings less valuable today and make it more expensive for companies to finance their growth.
However, all highly leveraged companies face the obvious problem that more expensive debt can eat into profits.
The housing industry is a prime example.
“Higher mortgage rates cool home sales and big ticket purchases, hitting homebuilders, furniture and related retailers,” Root said.
©2026 PG Publishing Co. Visit at post-gazette.com. Distributed by Tribune Content Agency, LLC.
Comments